For three years the private-equity fundraising market has had a simple rule. Investors write new cheques to the managers who have sent the old ones back. On Tuesday, Oct. 27, Advent International showed how well it has followed that rule.
The Boston- and London-based firm said it had raised $30 billion across its global fund complex. That includes close to $27 billion for its 11th flagship vehicle, Advent International GPE XI, which beat its $26 billion target. Advent says that makes it the largest buyout fund to finish raising in 2026 so far. It also includes more than $3 billion in commitments to Advent Mid-Market Private Equity, a new strategy launched in March.
The figure that matters most for the firm’s investors comes further down the release. Advent says 2026 has been among its strongest years for realizations. So far this year it has returned roughly $13 billion from 27 businesses and invested roughly $10 billion in 38 new and existing companies, counting closed and pending deals. In a market where many limited partners have spent two years waiting for distributions, a manager that returns more than it deploys has an easy conversation with them.
What the partners said
“In over four decades of investing, we’ve learned that when you partner with outstanding management teams to build lasting companies, great results follow,” said James Brocklebank, a managing partner and co-chair of Advent’s executive committee. “The trust our investors have placed in us in one of the most demanding fundraising environments reflects the consistency of our track record and our discipline in returning capital.”
His co-chair, John Maldonado, put the emphasis on specialization. “Our strength lies in deepening the sector expertise that has defined us as we grow our fund complex and bring new ideas and technologies to every stage of our investments,” he said. That expertise, he added, “coupled with teams across the world who understand the nuances of their local markets, remains the foundation of how we find and win differentiated opportunities.”
The commitments came from public and private pensions, sovereign wealth funds, endowments and foundations, institutional fund managers, family offices and wealthy individuals. Advent did not name any of them or say how much came from new investors versus existing ones. The release says only that a “meaningful number” were new to the firm.
The flagship and the new fund
GPE XI follows the strategy of its predecessors. It can invest across regions, sectors, deal types and sizes, with a focus on Europe and North America. It will keep building Advent’s presence in Asia Pacific and draw on its Latin American team. Advent has more than 290 investment professionals across five core sectors: business and financial services, consumer, healthcare, industrial and technology. It says it will keep pursuing the transactions it is best known for, corporate carve-outs and public-to-private deals.
The mid-market fund is the more novel product. It is Advent’s first vehicle dedicated to smaller buyouts and growth investments. It will write equity cheques of $100 million to $350 million into companies worth up to $1.25 billion, mainly in North America and Europe. Crucially, it will use the same deal teams as the flagship. Advent is betting that its sector specialists can find good smaller companies on the same rounds that turn up big ones, and that investors would rather buy that pipeline than see it go to waste.
There is an obvious question with any such arrangement: when a deal could fit either fund, who decides which one gets it? The release does not address allocation policy. Investors in both funds will want to know the answer, and it is the sort of thing a limited partnership agreement usually spells out.
A firm going global, and a crowded week
Advent has been expanding its footprint while raising money. Since 2024 it has opened offices in Sydney and Tokyo, its first in Australia and Japan, and in Abu Dhabi, where it says it is deepening relationships with the region’s leading institutional investors. Early this year it strengthened its Hong Kong office as its base for Asia Pacific investor relations. The firm now oversees more than $109 billion across 18 offices, according to figures as of June 30.
Advent’s announcement lands in an unusually busy fortnight for big closes. On October 19, Blackstone said its fifth energy-transition fund had closed at its $8.7 billion hard cap. Two days later, Pantheon said its eighth global secondaries programme had raised $6 billion, well above its $3.5 billion target.
The common thread is that capital is flowing to managers with a clear specialty or a record of returning cash. Advent’s numbers put it in the second group. Sceptics will note that one strong year of realizations does not prove that 2021- and 2022-vintage deals will all come good. Those were bought at the peak of valuations, and every large buyout firm still holds some of them. They will also note that $27 billion is a great deal of money to put to work at a time when sellers’ price expectations remain high.
The test ahead
Fundraising is the reward for past performance. The next five years will judge GPE XI on what Advent pays for its deals and how well it runs the companies it buys. The firm’s history of carve-outs, in which it buys a division from a large company and sets it up on its own, suits a period of active corporate restructuring. Public-to-private deals suit a period when many mid-sized listed companies trade below what their owners think they are worth. Advent is betting that both conditions will last.
For now, Advent has done what most of its peers have found hardest. It has returned capital, raised more than it asked for and opened a new line of business in the process. The investors who committed will be watching the distribution notices as closely as the deal announcements.
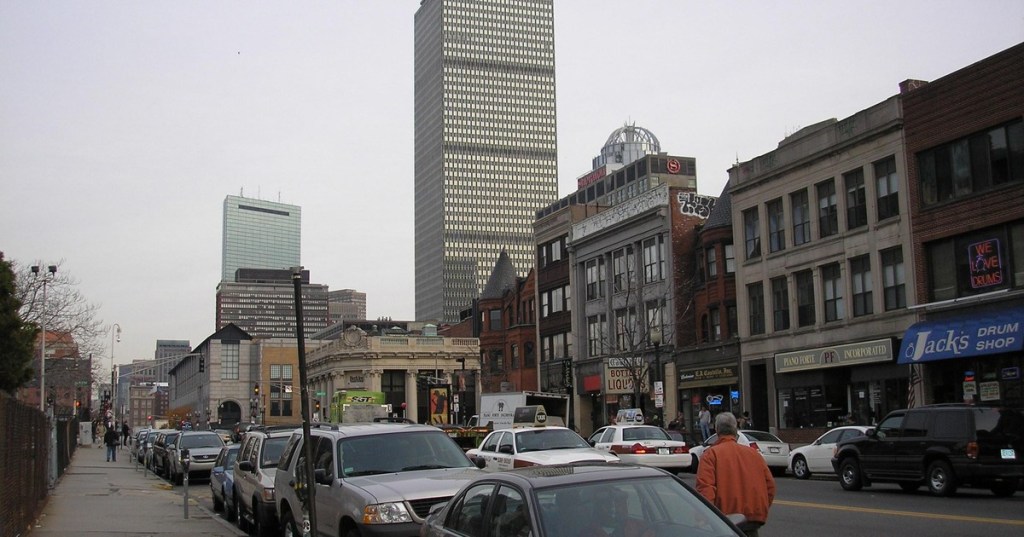
Featured image: The Prudential Tower in Boston, home of Advent International’s headquarters at 800 Boylston Street. Photo by Mustaqbal via Wikimedia Commons, public domain.



Leave a Reply