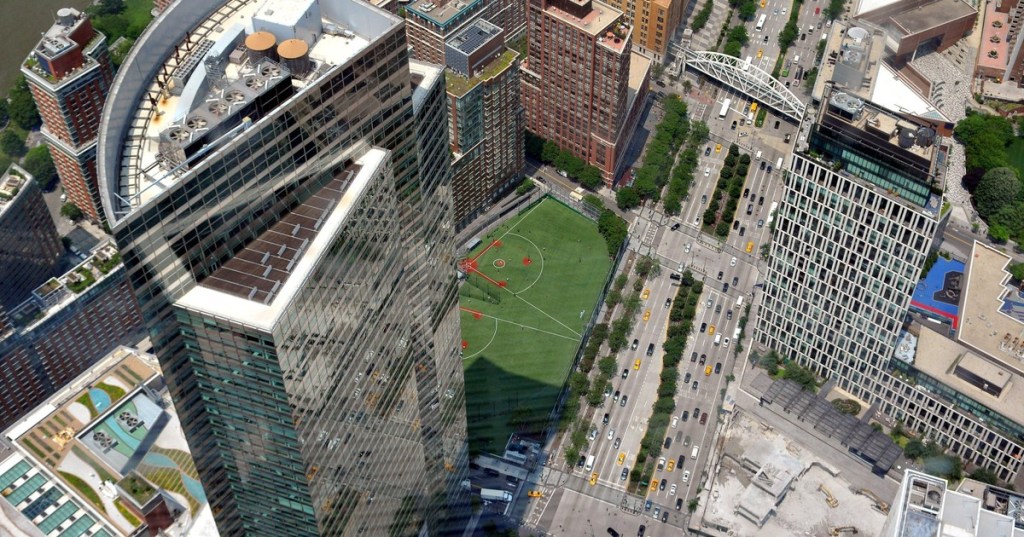
There is a particular kind of quiet that settles over 200 West Street when the league tables come out and the firm is on top of all of them. Nobody says anything, and everybody knows.
This autumn the quiet is deafening. By Mergermarket’s count, Goldman Sachs advised on $1.53 trillion of announced M&A in the first nine months of 2026, up 33.9 percent from a year earlier, giving it a share of 44.3 percent of a global market that itself came in at $4.4 trillion. JPMorgan was second at $1.11 trillion; Morgan Stanley third at $1.02 trillion. They are, as Mergermarket put it, the only three houses to clear a trillion dollars, which makes the race for fourth place a different sport entirely.
GlobalData, which counts somewhat differently, reached the same verdict on value: Goldman first with $687.6 billion across 154 deals, Morgan Stanley at $659.9 billion across 212, JPMorgan at $492.5 billion across 165, Bank of America at $315.1 billion and Evercore, the best-placed independent, at $278.7 billion across 133. On sheer number of transactions, the crown went to Houlihan Lokey, with 250 deals, which tells you something about where the middle market’s plumbing actually runs.
The money behind the rankings
League tables are a vanity metric until they show up in revenue, and this quarter they did. Goldman’s third-quarter earnings release, filed with the SEC on October 13, reported investment banking fees of $3.22 billion, up 21 percent from a year earlier. Advisory revenue was $1.65 billion, which the firm described as a quarterly record, up 18 percent. Equity underwriting rose 43 percent to $666 million; debt underwriting was up 15 percent to $904 million.
The reason advisory leads the line is mechanical as much as anything. Fees are booked when deals close, and the megadeals announced in the first half are now closing. Mergermarket counted 60 transactions above $10 billion so far this year, accounting for a record 35 percent of global volume. When the elephants move, the firms that represent elephants get paid.
The fine print
It would be a poor reading of the tables, however, that stopped at the top line. The same Mergermarket report noted that third-quarter volume fell 7 percent year over year and deal count fell 16 percent. Thirteen of the top 20 advisers by deal count recorded declines. Sponsor buyout volume, at $584.2 billion, was down 11 percent, even as private-equity exits rose 12 percent to $605.3 billion, which is what happens when limited partners stop asking politely for their money back.
Mergermarket’s own credentials as a skeptic are worth noting, too. Some of Goldman’s tally reflects defense assignments, which the data provider flagged with what it called “a slight health warning”: a firm hired to fend off a bid gets credit for the bid’s size whether or not anything changes hands.
The bifurcation is the story beneath the story. Megadeals are being done by giant companies, advised by giant banks. The mid-market, where most bankers in this city actually spend their days, is choosier and slower. Mergermarket put part of the hesitation down to private-equity investment committees “burned by longer hold periods and cautious against the backdrop of AI disruption.”
And there is Washington. Dealmakers told Mergermarket all year that they hoped to sidestep any political fallout from a contentious midterm campaign. That is a fair worry in either direction. A Republican Congress would likely keep the current deregulatory, merger-tolerant posture of federal antitrust enforcers; a Democratic House would bring more oversight hearings and more pressure on the agencies. Neither party has a monopoly on populist suspicion of big deals, as anyone who has listened to Senate Republicans on Big Tech or Senate Democrats on grocery mergers can attest. The bankers’ prayer is simply for a quiet November, which is a prayer they say every two years.
Bonus math
The people who do the work are already doing arithmetic of their own. In August, the compensation consultancy Johnson Associates projected that advisory bankers, M&A included, could see bonuses rise 15 to 20 percent this year, with equity sales and trading up 20 to 30 percent or more, according to Axios, which reported the firm’s view that 2026 was shaping up as “the year of the bank.” Private markets, by contrast, lag: bonuses at private-credit firms were projected flat to down 10 percent.
There is a catch, and it is a sober one. Alan Johnson, the firm’s managing director, told Bloomberg that banks are using artificial intelligence to trim headcount, and that the hiring that normally accompanies a boom is not materializing. “The people that survive are going to make more,” he said, according to the firm’s summary of the interview. Those “that remain will be treasured more, mentored better, though it will be harder to get a job.”
For the analyst classes now working their way through Murray Street dinners and 2 a.m. model turns, that is a split verdict: richer, fewer and more watched. For Goldman, which has spent the better part of a decade explaining its consumer-banking detour to shareholders, it is something closer to vindication. The firm went back to being what it was, and the market rewarded it for remembering.
The fourth quarter will tell whether the third-quarter slowdown was a breath or a turn. The banks themselves say pipelines remain full; the data say the mid-market remains thin. Until those two statements converge, the most useful thing to watch on West Street is not the rankings but the closing calendar, because that is where the bonuses are actually decided.
Featured image: Goldman Sachs headquarters at 200 West Street, Lower Manhattan. Photo by http://www.Pixel.la Free Stock Photos via Wikimedia Commons, CC0.


Leave a Reply